All Categories
Featured
Essential Travel Health Insurance for Pre-Existing Condit...
Integrating Life Insurance with Special Needs Trust Planning
Integrating Life Insurance with Special Needs Trust Planning
Table of Contents
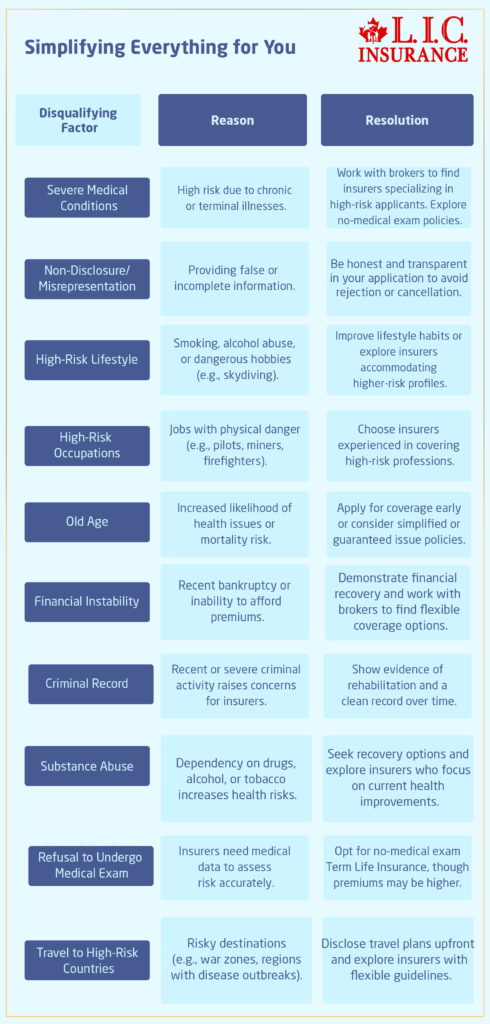
A pre-existing health condition doesn't imply you can't receive a life insurance policy, however it simply affects your readily available choices and pricing. Major conditions such as cancer or a previous cardiac arrest might place you in a higher-risk category, many individuals presume that they don't get approved for protection.
You still have choices and that's when impaired risk life insurance coverage enters into the image. It lets you get protection aligned to your danger element. Remember: You can get life insurance coverage with a medical condition. It's not constantly about the condition but what really matters is the intensity, date of medical diagnosis and how it's handled.
Whether you have medical or non-medical high-risk elements, you still likely have choices. The secret is to match the policy alternatives to your goals and current monetary or personal scenarios.
It is a hassle-free alternative for those with crucial health problems seeking ensured approval but at a greater premium and lower coverage quantity.
Not all insurers may offer similar coverage options and guaranteed concern is not your only option. Different insurance companies might examine danger in a different way, so constantly compare quotes.
Timing matters, so wait if your condition is improving to certify for much better choices later on. Even as an impaired-risk applicant, you may still be able to get protection.
Here are some pointers you may follow: Make sure that your condition is well managed and you follow the treatment plan. Avoid applying right away after a condition is identified.
Download and finish any appropriate surveys indicated based off the preliminary questionnaire.
Specialized Coverage for Post-Treatment Cancer Survivors
Life insurance coverage can be complicated, particularly when it comes to underwriting. Many individuals have a hard time to comprehend the procedure and are typically misled by typical misconceptions. This article looks for to clarify life insurance coverage underwriting by providing clear, precise information to assist you make informed decisions. It has often been stated that underwriting is a really fancy and lengthy procedure.
Most business now use quick underwriting alternatives, which permit you to minimize the time essential to get insured. This indicates you might get protection the fastest method without compromising on thoroughness in its appraisal. Stay ahead of the market with exclusive function stories on the top companies, expert insights and the most recent news delivered directly to your inbox.
While it holds true that health plays a big role in underwriting, insurance companies think about numerous elements, consisting of age, way of life, and family medical history. Even if you have some health concerns, you can still find competitive rates tailored to your circumstance. It's everything about finding the best policy that matches your needs and situations.
Life Insurance Critical Illness RiderEach policy type, the quantity of coverage you desire, and the analysis will depend on it. For numerous policies, specifically those with lower coverage amounts, the procedure can be simple and does not require much time. Some even offer no-exam policies, which rely on existing medical records and other information and make decisions based upon that.
Insurers are keen to provide cover to as numerous people as possible. To this end, they need to ensure that these premiums will be based on the level of the threat. Accurate assessment of one's danger will enable underwriters to use a policy that safeguards one at a fair cost.
2026 Policies for HIV Positive Applicants
When you're taking a look at life insurance coverage choices, you'll likely want the very best worth for the finest rate. Medical underwriting is one aspect that may affect what you spend for your life insurance premium. It involves your health and household medical history and can increase or reduce your payments. Let's take an appearance at how medical life insurance underwriting can affect your policy.
Answers to concerns like, "Do you smoke?" or "What pre-existing conditions do you have?" when you're requesting insurance coverage may impact your premium. In the case of medical insurance, the healthier you are, the less you'll most likely have to spend for your premium. Medical underwriting is a comparable process for life insurance.
1 The insurer takes a look at medical history, way of life routines, demographics, and other elements related to medical requirements. After an insurance company collects medical details, an insurance business will utilize analytical analysis to figure out the candidate's rate class and make a suggestion that best fits their circumstance.
Medical underwriting3 is just one part of the entire life insurance underwriting procedure. Life insurance business frequently likewise take a look at financial status, such as earnings or personal bankruptcy history, during the life insurance underwriting process. These factors assist an insurer offer the finest rate based upon your unique financial scenario.
Without confirmation that medical history and other factors involving life insurance do not present a risk, a life insurance coverage company might charge a greater premium to stay secured. Depending upon how high of a danger an insurance company figures out a candidate to be, a premium might be lower or higher than average.
Life Insurance Critical Illness RiderNew Policies for HIV Positive Applicants
In many cases, like when medical underwriting is not a requirement, life insurance underwriting may be completed in just 24 hr. In others, the life insurance underwriting procedure can take a couple of days to numerous months. The length of the medical underwriting procedure for life insurance varies. If red flags appear in an application, an underwriter may take more time to examine.

Latest Posts
Navigating Impaired Risk Underwriting in the US
Essential Travel Health Insurance for Pre-Existing Conditions
How to Find the Right High-Risk Policy