All Categories
Featured
Essential Travel Health Insurance for Pre-Existing Condit...
Integrating Life Insurance with Special Needs Trust Planning
2026 Trends in High Risk Insurance Markets
Table of Contents
Why you can trust Quality Verified At, we are committed to providing the timely, precise and expert info customers need to make smart insurance choices. Our group thoroughly vets our rate information to ensure we just supply trustworthy and current insurance rates.
Our content is based entirely on objective research and data event. We preserve stringent editorial self-reliance to make sure impartial coverage of the insurance coverage industry.
Cancer patients only qualify for an ensured life insurance coverage policy with restricted coverage and limited payments during the initial years. Cancer survivors who recuperated and have actually been in remission for at least 5 years can get a conventional term or long-term life insurance policy, depending on the seriousness of their medical diagnosis.
Last expenditure insurance coverage offers a typically low amount of coverage however still provides funds to cover medical expenses or a funeral. If you're in remission, then insurers might use you traditional coverage, however it depends upon a couple of elements: The date you were diagnosed The kind of cancer you had The stage of cancer you had Your treatment history Before they underwrite a policy, a lot of insurance providers will use guidelines from the National Cancer Institute's "Monitoring, Public Health, and Outcome" (SEER) database.
The report also includes predicted survival life tables that detail survival statistics for different groups who are in remission. Insurance providers will use this information, as well as specifics about your particular case and diagnosis to determine what kind of policy you certify for or if you qualify at all. Some life insurance coverage business may be unwilling to supply protection for someone with a history of cancer, however there are plenty of others who want to do so.
Evaluating Standard Versus Impaired Risk Coverage
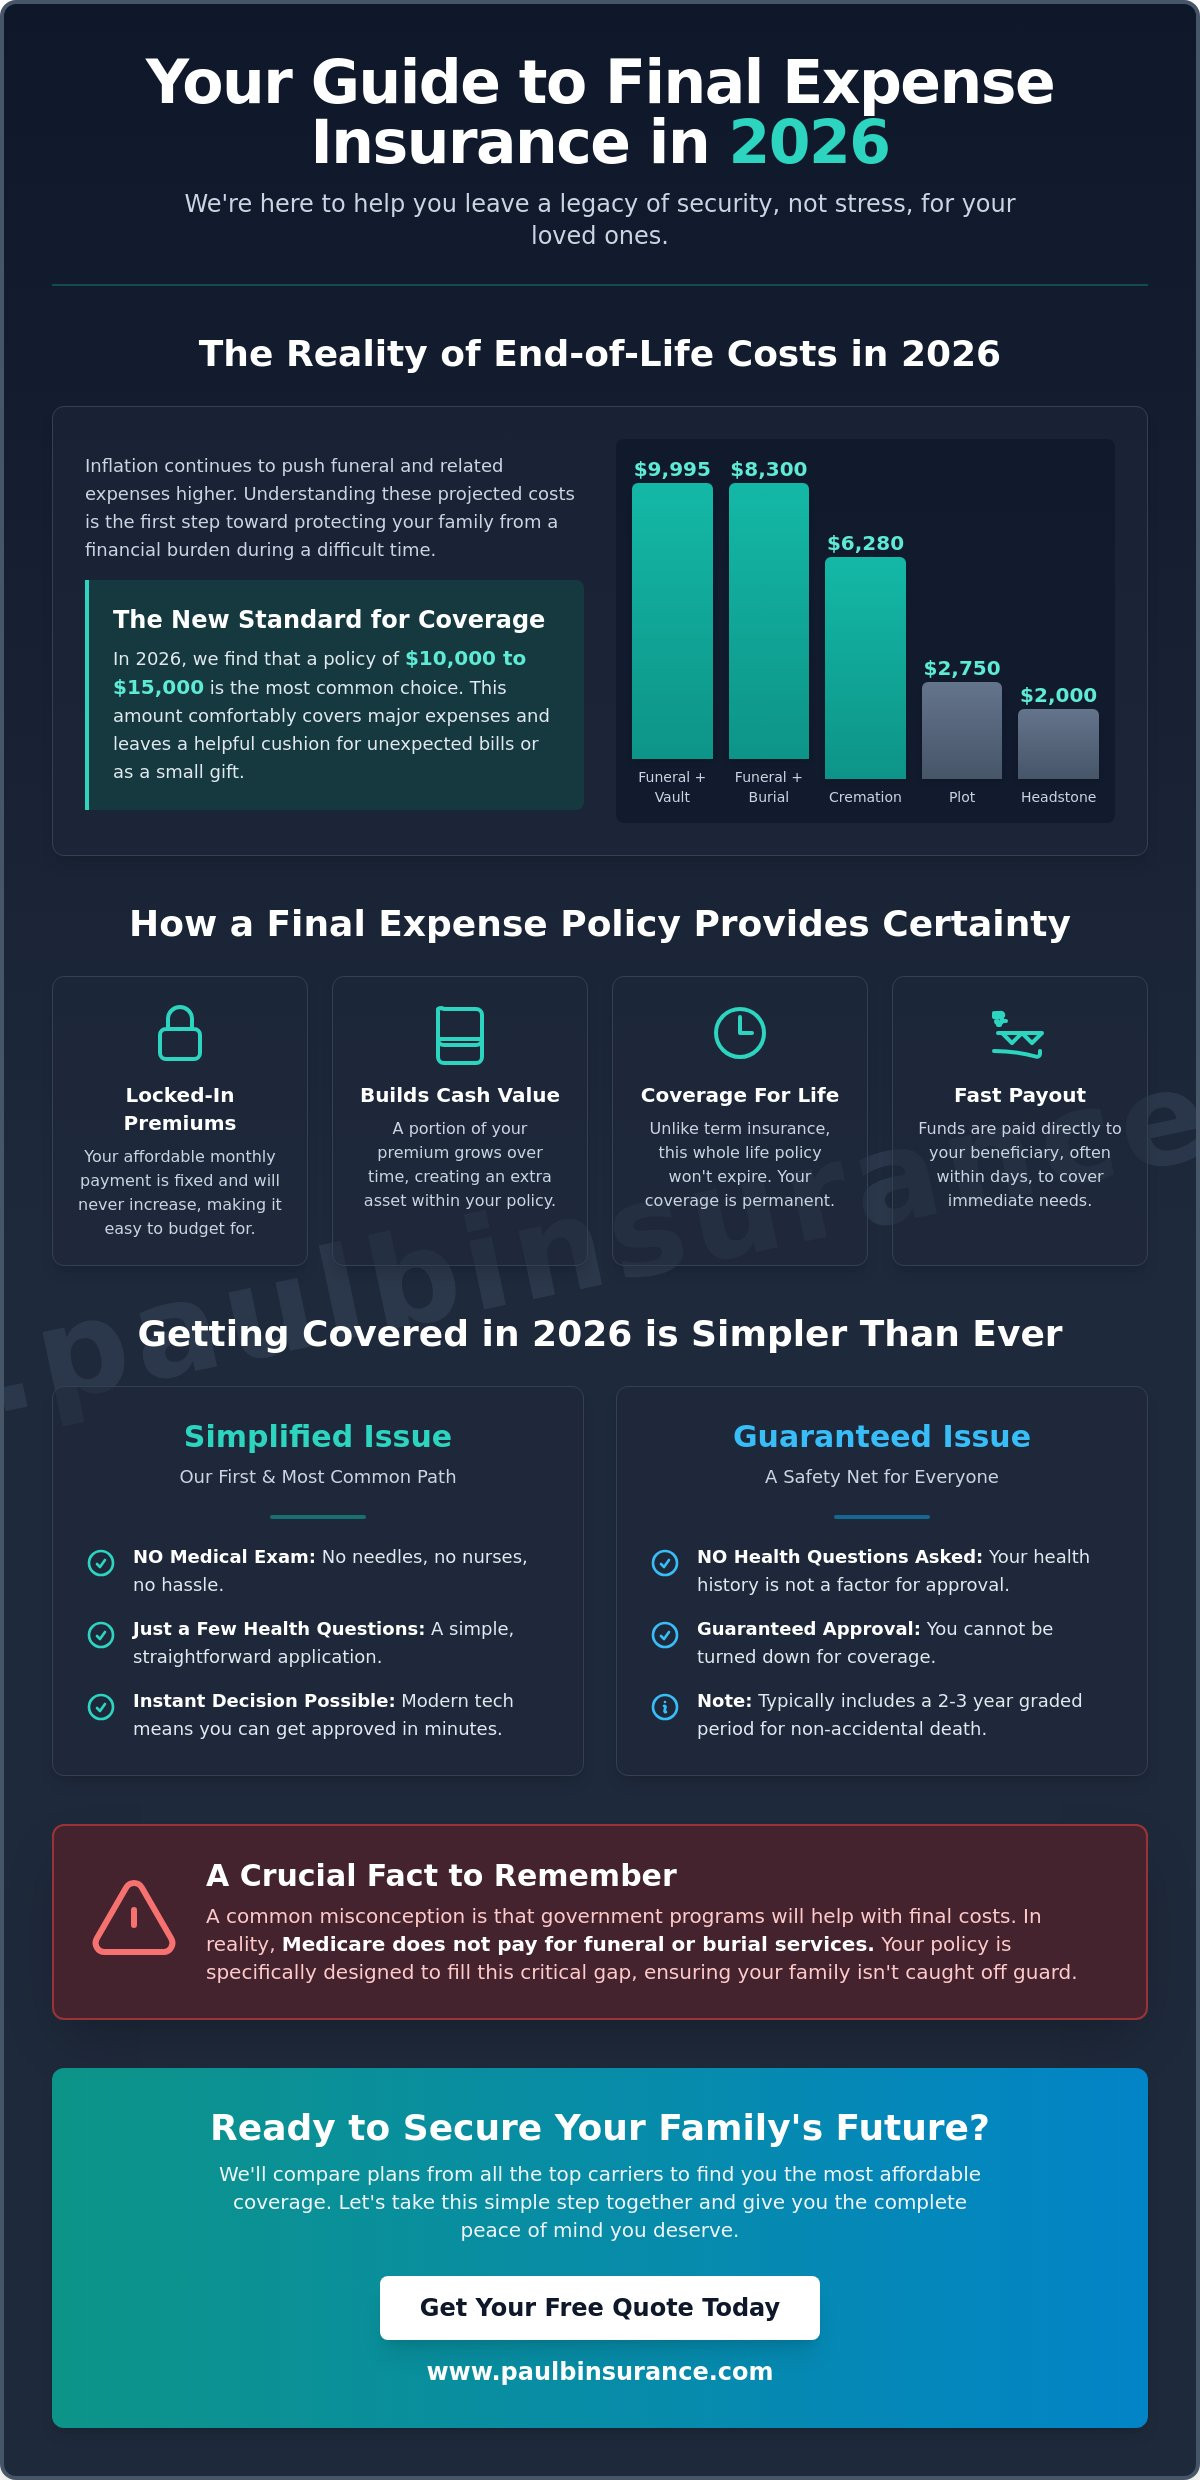
Make sure to get quotes from numerous companies so that you can compare rates and coverage alternatives. Final expenditure life insurance coverage policies are typically more costly than other policies and do not need a medical examination or health concerns. This makes them ideal for individuals with pre-existing conditions like cancer.
Special Needs Plan AdvisorNevertheless, the trade-off with last expense insurance coverage is that the policy amounts are relatively low compared to traditional life insurance. Generally, a last expenditure policy may have a face value that ranges from $5,000 to $50,000. There are 2 kinds of last expenditure insurance: Streamlined concern term insurance coverage is a kind of life insurance that provides insurance quickly.
To get a simplified life insurance coverage policy, you simply require to address a few medical concerns. Another choice is an ensured issue policy, which does not include any medical questions.
For circumstances, if you have a more challenging diagnosis, an insurance company might categorize you as substandard. This could result in either being rejected protection or just qualifying for a considerably more costly policy, even if you have a more beneficial prognosis or the cancer remains in its early phases. Being diagnosed with certain cancers in fact might not harm your possibilities of getting a policy.
Empathy-Driven Medical Underwriting Best Practices
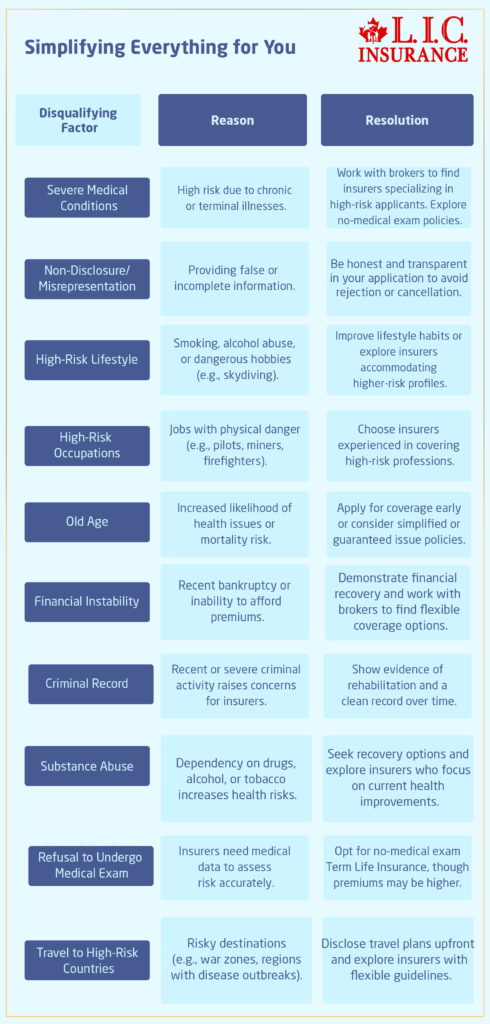
Each life insurance coverage company has its own requirements for coverage, so while some may use you a policy, others might not. That's why it's important to compare choices and search to discover the best suitable for your scenario. In addition, it's a great idea to deal with a life insurance coverage agent if you have a history of cancer.
Special Needs Plan AdvisorA skilled agent knows which insurers are more accommodating to your particular medical history, ensuring you get the finest rates and protection possible. The protection limitations on these policies are typically lower.

Latest Posts
Navigating Impaired Risk Underwriting in the US
Essential Travel Health Insurance for Pre-Existing Conditions
How to Find the Right High-Risk Policy